
Truist Mobile
- Rating
- 4.8
- Downloads
- 1.00M
- Content Rating
- Everyone
Truist Mobile - Screenshots
Pros
- Quick fingerprint or Face ID login on supported devices.
- Card controls let you lock and unlock a misplaced debit card.
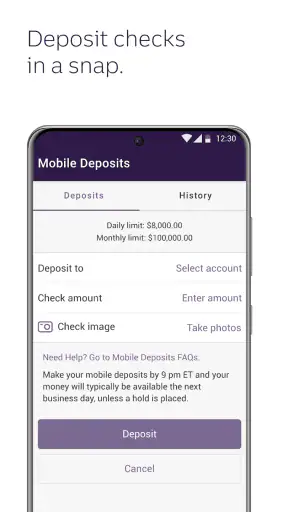
- Mobile check deposit includes useful status tracking after submission.
- Bill pay supports scheduled and recurring payments from the app.
- Custom alerts help monitor balances
- transactions
- and suspicious activity.
Cons
- Some features may vary depending on your Truist account type.
- Mobile check deposits can be subject to limits and extended holds.
- The app may request frequent security verification on unfamiliar devices.
- Certain support issues still require contacting a representative by phone.
- Performance and availability can vary during maintenance or peak periods.
Truist Mobile - Description
- App Name
- Truist Mobile
- Package Name
- com.truist.mobile
- Developer
- Truist Financial Corporation
- Category
- Finance
- Last Updated
- Apr 27, 2021
- Version
- Varies with Device
I spent time using Truist Mobile as a day-to-day banking app, paying close attention not only to the usual account tasks but also to how comfortably different people can read, navigate, and complete them. Developed by Truist Financial Corporation, this free finance app is aimed at customers who want to handle banking from a phone instead of relying on a branch or desktop browser. It is available for users aged Everyone, supports Android 9 and later, and has built a strong audience with an average rating of 4.8 from around 382 thousand ratings and more than 1 million installs.
My overall impression is that it works best when you already use Truist and want a practical mobile companion for routine money management. The experience is familiar enough for everyday banking, but the real question is not simply whether it can replace a branch visit. It is whether the app lets you complete important tasks with enough clarity and control when your circumstances are different: when your eyesight is tired, when one hand is occupied, when you are in a noisy place, or when a small mistake could create real financial stress.
How clearly the app supports different users
Readability and navigation during ordinary banking
The first thing I noticed is that a finance app has to make hierarchy do most of the work. Balances, account choices, transfers, and payment actions should not compete for attention. Truist Mobile generally feels designed around that practical sequence: open the app, identify the account you need, check the relevant information, and choose the next action. That is a better approach than filling the opening screen with promotional material or secondary tools.
For someone who checks a balance several times a day, this straightforward structure matters more than decorative design. I found it easier to think in terms of “what do I need to do now?” rather than “where has the app hidden the banking function?” That makes the app approachable for people who are not especially confident with technology, including users who prefer repeating a small number of familiar routines instead of learning a complicated financial dashboard.
Readability is also about reducing interpretation. A balance should be distinguishable from a transaction, and an account should be distinguishable from an action that changes money movement. In my experience, the app is most comfortable when I slow down and treat each screen as a confirmation point. Banking interfaces reward that habit because tapping quickly can be costly. I would not recommend rushing through the screens simply because the layout feels familiar.
The app is a good fit for a person who wants mobile access to an existing Truist relationship, but it is less useful as a general-purpose financial organizer for someone who keeps accounts across several institutions. A bank-owned app naturally focuses on its own services. If your main goal is to see every card, loan, investment, and outside account in one combined view, a dedicated money-management tool may offer a broader perspective.
One useful habit is to separate checking from confirming. I use the opening view to see whether something looks unusual, then open the relevant account and inspect the transaction details before deciding what to do. That small pause is especially helpful for users with attention difficulties or anyone managing money under pressure. It also reduces the chance of confusing a pending item with a completed one, although the exact information shown can depend on the transaction and account context.
Motor and sensory considerations
Mobile banking can be difficult for people who have limited dexterity, tremors, reduced reach, or difficulty maintaining a precise touch. Truist Mobile benefits from a workflow that usually involves ordinary taps and short decisions rather than constant text entry. That makes it more manageable than a process that asks users to type long forms for every small task. Still, financial actions deserve deliberate tapping, so I would avoid using it while walking or while holding the phone awkwardly.
A practical workaround is to prepare before starting a sensitive task. I keep the phone stable, make sure the screen is free from glare, and avoid beginning a transfer when I am distracted. This is not a special feature of the app, but it changes the experience considerably. For users with motor limitations, a stand, a larger device, or an operating-system accessibility setting may make the difference between a comfortable session and repeated accidental taps.
People with low vision may find the app easier when the phone’s display settings are adjusted for their needs, but enlarged text or stronger contrast can affect how much information fits on a screen. That trade-off is important in banking: larger text can improve reading while also requiring more scrolling. I would test those settings on a low-risk screen first, then confirm that account names, amounts, and action buttons remain easy to distinguish before carrying out a payment or transfer.
For users who rely on screen readers, the safest approach is to test the complete journey rather than assuming that one accessible screen means every banking action will be equally comfortable. Account summaries, transaction details, authentication steps, and confirmation messages each serve a different purpose. I would make a small, familiar check first and keep the phone’s spoken feedback active until the final confirmation has been understood.
Sensory overload is another consideration. Financial apps can feel stressful when alerts, unfamiliar wording, or multiple choices arrive at once. Truist Mobile is most usable for me when I approach it with one job in mind. Checking a balance, reviewing a charge, and arranging a payment are separate sessions in my routine. That simple separation makes the app feel calmer and gives users who process information slowly more time to verify each decision.
Situational access beyond the ideal setting
The strongest test for a banking app is not a quiet room with plenty of time. It is the moment when I need information while travelling, waiting for an appointment, or dealing with an unexpected expense. Truist Mobile is valuable in those situations because a phone is usually closer than a computer. I can review my account context before making a decision instead of relying on memory or guessing how much money is available.
That convenience should not be confused with universal access. A phone may have a weak connection, low battery, a damaged screen, or a security lockout. A user may also be in a place where privacy is limited. I would not open detailed financial information on a shared screen or in a crowded setting unless I can control who is looking. The app makes banking portable, but portability creates its own privacy and concentration challenges.
Consider a realistic example: I am at a pharmacy and the total is higher than expected. Rather than abandoning the purchase or repeatedly guessing, I can check the account I normally use and decide whether the expense fits my plan. If I need to investigate a recent charge, I can look at the transaction context instead of calling a branch immediately. For a user with mobility limitations, that kind of remote check can remove an unnecessary trip and make an ordinary errand more manageable.
Another useful workflow is preparing for a recurring obligation before the due moment. I review the account that will be used, check recent activity, and make sure I understand which action I am about to confirm. This is particularly helpful for people who need extra processing time or who find last-minute decisions difficult. The app is not a substitute for personal budgeting, but it can shorten the distance between noticing a problem and responding to it.
At the same time, I would not rely on a mobile session as the only plan for an urgent financial dispute. If the phone is unavailable or the app becomes difficult to use, a customer needs another route to support. People who need face-to-face assistance, extensive explanation, or help from a trusted person may still prefer a branch or phone conversation. Truist Mobile adds independence, but it should not be treated as proof that every banking situation can be solved inside the app.
Where friction can remain
The biggest limitation is inherent to mobile banking: a small screen leaves less room for context than a desktop browser. When a transaction list is long, reviewing several entries can take patience. When a form or confirmation contains multiple pieces of information, I prefer to read everything before tapping. Users with memory, concentration, or vision challenges may find it tiring to move between screens and retain details.
Authentication can also be a point of friction. Security steps protect financial information, but they can be harder for people who have limited dexterity, difficulty reading codes, or trouble switching between apps and messages. I see this as a necessary tension rather than a flaw unique to Truist Mobile. The best response is to avoid starting a sensitive task when rushed and to keep an alternative support route available if the sign-in process becomes inaccessible.
Another barrier is familiarity with banking language. Even a clean layout cannot remove the need to understand terms such as available balance, posted activity, or transfer destination. A first-time mobile banking user should take time to learn what each screen means before moving money. If you are helping a relative, I would teach the difference between viewing information and authorizing an action, then let that person perform a harmless practice check independently.
Users who manage finances jointly may also need a clear personal routine around privacy and consent. A convenient app can make it tempting to hand a phone to someone else for assistance, but that may expose more information than intended. I recommend deciding in advance what kind of help is acceptable, keeping the device locked when it is not in use, and reviewing the final confirmation personally whenever possible.
The app is also not the best choice for everyone in the finance category. If you are comparing products from multiple banks, building detailed household forecasts, or looking for a broad investment dashboard, a specialized service may be more appropriate. If you rarely use mobile devices, a desktop browser or branch interaction could be less stressful. Truist Mobile makes the most sense when your main need is direct access to Truist banking from a phone, not when you want an institution-neutral command center.
Everyday strengths that are easy to overlook
One of the less obvious strengths is the way a focused bank app can support a “verify before acting” routine. I can begin with a quick account check, inspect the relevant activity, and only then decide whether a payment or transfer is sensible. That sequence is more useful than simply having many tools available, because it encourages a pause between seeing a number and changing it.
A second insight is that accessibility often depends on session design. I get a better result when I use the app for one purpose at a time, increase the phone’s text size before I need it, and keep the device on a stable surface. Those choices reduce cognitive and motor demands without requiring a user to become an expert in banking technology. They are especially useful for older adults and people whose ability changes with fatigue or pain.
A third trade-off is between independence and support. The app can let someone complete a routine check privately instead of asking another person to call or visit on their behalf. But if a user needs help interpreting a transaction, a second person may still be valuable. I would use assistance for understanding, not for casually taking over the phone, and I would make sure the account holder remains the person who reviews and confirms the action.
The app’s free price removes a direct cost barrier, which makes it easier to try as an extension of an existing Truist account. That does not mean every banking service or account relationship has the same terms, so I would separate the cost of using the app from the financial conditions of the products accessed through it. For a person deciding whether to install it, the relevant question is whether Truist is already their bank and whether mobile access would remove a practical obstacle.
My inclusive verdict after using it
I see Truist Mobile as a sensible choice for Truist customers who want a direct, familiar way to monitor and manage everyday banking from a phone. Its value is strongest for routine checks, quick decisions during errands, and users who benefit from avoiding unnecessary travel. The app’s broad adoption and strong average rating suggest that many people find the overall experience dependable, but those figures should not replace a personal accessibility test.
For me, the most inclusive way to use it is intentionally slow: adjust the phone for comfortable reading, complete one task at a time, inspect details before acting, and read the final confirmation. That method helps with screen fatigue, distractions, motor precision, and financial anxiety. It also makes the app less intimidating for someone moving from branch banking to mobile banking.
I would recommend trying it if you already bank with Truist and want more independence during ordinary financial tasks. I would be more cautious if you need a highly specialized budgeting system, manage many unrelated institutions, or depend on assistance that the mobile interface cannot easily provide. In those cases, a desktop, branch, phone support, or another financial tool may be better alongside the app.
Released on April 27, 2021, and available to users on Android 9 or later, Truist Mobile has had time to become a familiar part of the bank’s digital experience. My final view is positive but practical: it is most inclusive when treated as a clear tool for controlled, everyday actions rather than a complete answer to every banking need. Used with sensible privacy habits and enough time to verify each step, it can make banking noticeably easier without pretending that a phone screen works equally well for every person or situation.
FAQ
What is Truist Mobile, and what can I do with it?
Truist Mobile is the official mobile banking app for Truist customers. After signing in, you can review account balances and transactions, transfer money between eligible accounts, deposit checks, pay bills, manage cards, locate branches or ATMs, and contact support. Available tools may vary depending on your account type, location, device, and Truist’s current service availability.
Is Truist Mobile safe to use for banking and payments?
Truist Mobile uses security features designed to protect your banking information, including encrypted connections, login authentication, device security checks, and optional biometric sign-in on compatible devices. Even so, no banking app is completely risk-free. Download it only from Google Play or the App Store, keep your phone updated, avoid public Wi-Fi for sensitive activity, and never share verification codes or passwords.
Can I deposit checks through the Truist Mobile app?
Eligible Truist customers can generally use the app’s mobile check deposit feature by photographing the front and back of a properly endorsed check and submitting it for review. The image must be clear, and deposit limits, funds availability, endorsement rules, and processing times may apply. Keep the original check until the deposit is fully processed, then follow Truist’s retention guidance.
Does Truist Mobile charge fees for its main features?
Downloading and using the Truist Mobile app is generally not charged as a separate app fee, but normal account terms still apply. Certain services, transactions, overdrafts, wire transfers, expedited payments, or non-Truist ATM usage may involve fees depending on your account and circumstances. Mobile data or messaging charges may also come from your carrier, so review Truist’s current fee schedule before using specific services.
What should I do if I cannot sign in or the Truist Mobile app is not working?
First, check your internet connection and confirm that you are using the latest version of Truist Mobile from the official app store. Restarting the app or device may resolve temporary problems. If you forgot your credentials, use the official recovery options rather than third-party links. For locked accounts, suspected fraud, repeated errors, or service outages, contact Truist through the app, its official website, or the phone number on your card.


